2020年7月23日星期四

Dpharma 7148 联合药业RM 3.06投资。


转贴:

大马市值最高药业公司‧联合药业管理强 盈利稳

Clos
erkongseng


【 DPHARMA 简介】 

        DPHARMA 是一家制药公司,以生产仿制药(Generic medicine)为主。DPHARMA 的全名是 Duopharma Biotech Berhad (在今年才刚刚换名字) ,原名是 CCM Duopharma Biotech Berhad(本来的股票代号为 CCM)。以销售量(volume)来计算,DPHARMA 目前是大马领先的业者,目前占据整个仿制药市场的 6.5%,不过销售值却排名第 2,市值也为大马药剂第 2 大。 
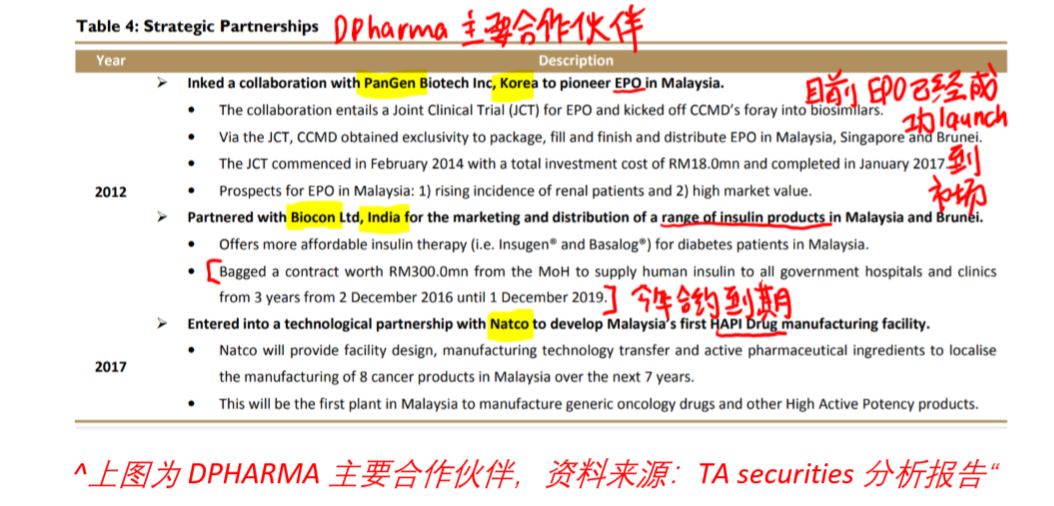
          DPHARMA 也与一些生物科技(biotech)公司联营来升级公司本身的生产厂。DPHARMA 目前是印度药剂公司 Biocon 的主要合作对象之一(这家公司是印度上市的药剂公司,市值排名第 8),共同生产一系列的胰岛素(insulin)到马来西亚,新加玻,和文莱。


       除此之外,DPHARMA 也与韩国的一家药剂公司 PanGen Biotech 成功开发了一种叫做Erythroprotein “EPO” 的生物仿制药(Biosimilar),这是一种红血球生成素。公司是在去年的 4 月购买这家 PanGen Biotech 8.39% 的股权,这个购权的用意是为了受惠于 PanGen 的生物科技技术,加强公司本身的开发产品能力。DPHARMA 在最新季报也表明了公司已经获得全国药品监管机构的注册批准,被允许销售这个“EPO” 产品,将以 Eryssa 品牌命名。EPO 是一种
人体内的蛋白质,它将结合人体内的红血球来提高人体氧气的吸收力,这种药物的疗效对于一些贫血症状的病人和肾衰竭十分有效。 


            据 2018 年报得知,DPHARMA 目前一共有 3000 位员工,他们都分布在首都吉隆玻的办公楼,Bangi ,Klang,Glenmarie 的生产厂,和菲力宾,新加玻,印尼的地区办事处。这三家生产厂房都受卫生部 (MoH) 的认证, 有达到 GMP 生产标准. 公司这几年都在积极升级位于 Taman Jaya Klang 和 Glenmarie 的厂房. 巴生新的厂房(K3) 将会取代旧的 K1, 目的是为了提高口服药物和特别产品的产量. 至于 Glenmarie 的厂房将会改造为新的 “HAPI” 厂房, 目的为了迎合与Natco 的合作. 由于 Glenmarie 的这个 Hapi 厂房主打的是一些仿制肿瘤学和其他 High Active Potency 的药物产品,公司预计会获得由政府颁发的 100% 收入税豁免. 


【 DPHARMA 筹码面】 


           DPHARMA 大股东内可以见到很多官联投资机构的踪影,其中最大股东就是国名投资公司(PNB),还有 Amanah Saham,EPF,是个名副其实的 “官联股” 。大家注意,本来DPHARMA 的原名是叫 CCM Duopharma Biotech Berhad(CCMB),但在前两年因为 CCM 企业重组,导致两个公司脱节不再有关系,这也是 DPHARMA 改名的原因之一。在此之前,PNB 本来是 CCMB 的最大股东,但就因为 CCMB 把 CCMB 分解出来,所以才导致 CCMB(也就是现在已经易名为 DPHARMA )PNB 持股比例被稀释为仅有的 45.186%。 


【 DPHARMA 产品组合】

             为了迎合大马马来人居多的人口比例,DPHARMA 专门主打清真的药剂产品,更是大马第一家获得由马来西亚伊斯兰教发展署(JAKIM) 颁发的 Halal 证书的公司,也在 2017 和 2018 年荣获“年度清真制药公司” 的奖项。除了专注在仿制药这个竞争激烈的红海市场,DPHARMA 也在这几年专注于生物仿制药市场(Biosimilars)这个缝隙市场。生物仿制药与普通药物不同之处在于它们是取之于动物和植物,而非化学生产,但其价格也会稍微比普通仿制药高一些。这是因为生物仿制药所治的症状都是稍微严重的,比如癌症,老年痴呆,和艾滋病等等。 
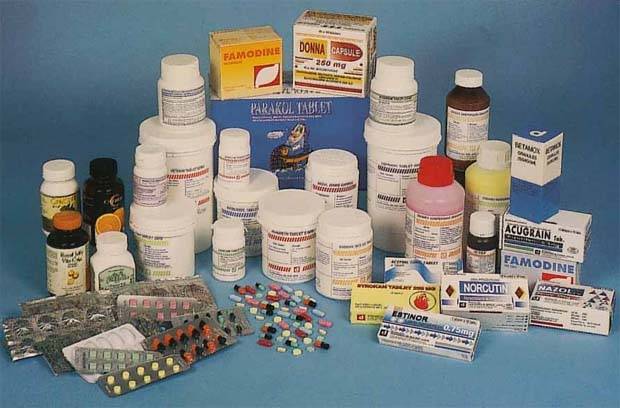
            目前 DPHARMA 的药物和补助品组合达到 437 种,当中包括 70 种消费性保健产品,止痛药,和 367 种仿制药。其中一些产品已经是大马人民熟悉的药物品牌,比如 Champs, Flavettes 和 Naturalle,这些都是一些大型活动比赛的时候举办当局送的环保袋会有的一些品牌,或是小学的时候拿回家学校送的礼物. 除此自外,公司也有一家专门做开发和研究 “R&D” 的研究所,由旗下子公司 Innovax Sdn Bhd 负责营运. 
           虽然公司最近一直在扩张业务以减少对本地政府合约的依赖, 但从筹码面和销售额来观察, 公司对政府合约还是十分依赖的, 据 TA securities 研究报告得知, 公司超过 50% 的销售额还是来自于政府,而且那么多官联投资机构都是公司的大股东,相信政府还是会持续办法合约给他们. 但大家要注意的是,政府颁发合约都是给 Pharmaniaga 先,然后再通过下一个竞标程序来派发合约给其他药剂公司.  

【 DPHARMA 基本面】

↑↑↑基本面数据取于Wealthpark 基本面分析软件 ↑↑↑
           
         DPHARMA 营业额虽然在近几年都保持高速成长, 但净利润却因为赚幅(profit margin) 的减少而导致净利润放缓 . 由于这几年积极的开发和扩张业务 , current ratio (应对短期债务的资产) 和 cash ratio 也减少了许多. 至于自由现金流(free cash flow) 也因为资本开支的提高开始减少。
         DPHARMA 在这几年的资产大幅增长, 原因是公司在 2015 和 2018 年进行了好几次的融资, 这几次的融资也导致公司的负债水平大幅提高. 至于股息方面则因为盈余的减少导致这几年股息的派发减少,不过从公司扩张业务的积极表现, 把这些盈余用于扩张业务是更明智的选择.  

【 DPHARMA 优势 】 

1. 政府在 2019 财政预算案提高了对医疗保健行业的支出, 其中 108 亿将会 用与诊所和医院, 将会间接提高对药物的需求, DPHARMA 身为大马药剂 业龙头之一将会受惠. 
2. 公司积极在红海市场中寻找被遗漏的生物仿制药市场,并把握商机,与国 内外大型药剂公司一起开发各种药物产品. 


【 DPHARMA 劣势 】 

1. 高度依赖单一顾客 (政府). 
 2. 外汇兑换风险, 公司一部分的成本都是以美元和欧元计算, 假如马币兑换 美元的汇率提高将会间接导致公司的成本变高, 盈利减少. 而且公司没有 任何货币对冲的政策来预防马币贬值的风险. 
3. 公司的主要销售产品都是仿制药,这个红海市场的竞争激烈,公司需要不 断地创新和积极寻找新的合约以提高市场占有率. 

【 个人观点 】 

           DPHARMA 目前正在积极开发新的市场和业务,导致公司的成本增加了不少,虽然营业额有明显的增幅,但利润却因为资本开支的提高反而减少了,加入公司能够有效控制成本并在未来
减少资本开支而任继续保持营业额的增长, 那盈利就会有望复苏.

个人分享,買卖自负。

2020年7月13日星期一

Notion 0083 Rm0.72投资。

转贴:

Notion: Face Mask & Polypropylene Fabric Biz - Bursa Dummy

Friday, 15 May 2020
Notion's 2:1 bonus issue just got ex-ed today. With yesterday's closing price of RM1.16, its opening price today should be 77sen. It ended the day at 83.5sen (up 8.4%) even though its day high was 91.5sen.
After falling to 40sen in Mac20, Notion has miraculously crawled back to its pre-Covid price range of around RM1.20.
Recently we could see lots of so-called "Covid-19 related" stocks rocketed into the sky. The party is even joined by a hospital beds provider.
Is Notion one of those stocks?
Not long ago, Notion's chairman mentioned that the company is venturing into face mask production business.
This leaves lots of question marks to investors. What kind of face mask? What is the scale of the production? When will it start? How much sales does it expect?
Yesterday, Notion finally published the detail of its face mask business on its website.
According to the presentation, Notion will produce 3-ply & 4-ply face masks, and also polypropylene melt blown fabric used to produce face mask.
It has invested in 3 lines which can produce a maximum of 8 million of 3-ply face masks per month. This is expected to start operation in June.
It will also add one line to produce 4 million pieces of 4-ply face masks per month in August.
For the polypropylene melt blown fabric (PPMB), it has invested 2 machines which are able to produce 20 tons per month starting from June, and another 2 machines which are able to produce 25 tons per month from August.
So, Notion can produce 45 tons of PPMB from August, but the chairman said that Notion has orders of more than 100 tons per month from ready buyers in China!
As a result, Notion will develop its own PPMB machines in 3 months to produce another 100 tons per month.
The estimated sales of face masks (12mil/mth capacity) and PPMB (45 tons/mth capacity) are expected to be RM11.2mil and RM6.3mil respectively, per month at full capacity.
If this is true, it will potentially contribute RM17.5mil sales per month, or RM210mil per year! This does not even fulfill China's order of more than 100 tons PPMB per month.
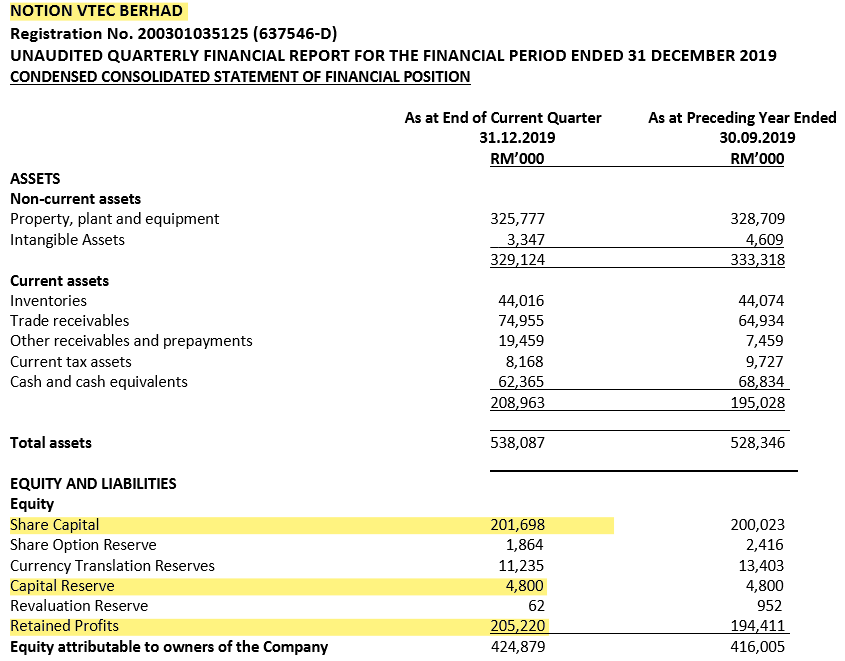
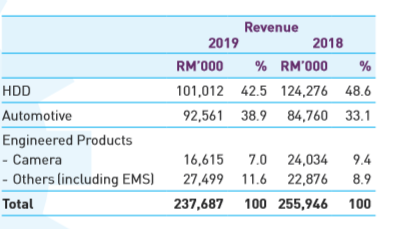
Notion's FY19 (ended Sep19) total revenue was RM238mil. So this face mask business will almost double its previous revenue derived from HDD, camera, auto parts etc...
Gross margin is targeted to be 30-50%.
When it announced its FY20Q1 result in Feb20 before the Covid-19 fear, Notion gave a target sales of RM320mil for FY2020, mainly helped by the new EMS & aluminium extrusion business.
It's not easy to predict Notion's EPS since its recent quarterly financial results are affected by insurance claims and one-off items.
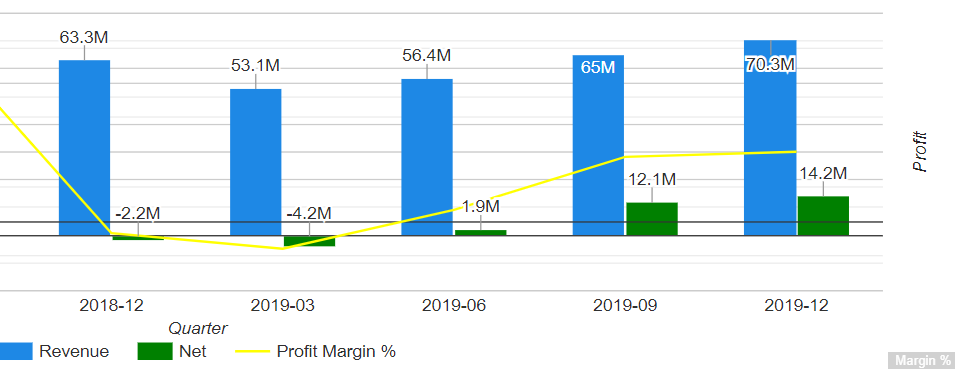
However, Notion's chairman did mention that its operating after tax profit for FY20Q1 was RM5.2mil from a revenue of RM70mil.
It will release its FY20Q2 (Jan-Mac20) result soon in early June. Of course its net profit will be much lower than the preceding quarter of RM14.2mil. 
Personally I hope its FY20Q2 net profit can be around RM5mil, which means an EPS of 1sen based on 504mil shares after bonus issue.
This figure is just a guess. If Q2 goes into red, I won't be surprise.
FY20Q3 is widely expected to be loss-making. Besides factory shut down, its existing business might be affected by cancelled or reduced orders from customers.
As the worldwide economy is gloomy in the near term, we are not sure how Notion's second half of calendar year 2020 will look like, but the venture into face masks business might come in time to keep the company busy and moving.
It does not need to rent a place as it just moved to its new and larger plant. It might not even need to hire more workers. 
Nevertheless, it might still suffer initial start up loss, who knows?
The demand for face masks is high now, but we don't expect this to last forever.
When the demand wanes, at least it has kept Notion afloat during the crisis, ONLY IF everything the management plans goes well.

2020年7月6日星期一

Comfort,ruberex可以收,会上4元之上.


Coronavirus: Mapping Covid-19 Confirmed Cases and Deaths Globally
https://www.bloomberg.com/graphics/2020-coronavirus-cases-world-map/


转贴:
Comfort AGM-文庆
作者:Tan KW发布日期:星期二,2020年6月30日,晚上11:20

文庆从“管理我们的财务” fb页面复制。

用于阅读目的。这不是*买/卖电话*

舒适年度股东大会。

1)Comfort在2020年和2021年将增加几条生产线?
我们将增加5条生产线,总共58条生产线,这5条新生产线将增加6亿只手套。总共会有6b手套。

2)您如何与其他手套公司竞争?
我们专注于专业手套,这使我们与其他手套制造商有更多不同,我们还与客户紧密合作并生产满足他们要求的手套

3)手套的当前价格是多少?
去年的价格是22美元,上一季度是25-27美元,其次是30-35美元。我们将继续每月平均增长5-10%。

4)Comfort投资于自动化系统。这对公司有多大帮助?
自动化使我们的运营更有效率。我们分步实施自动化,以避免过多地影响日常运营。实施自动化后,我们的人工成本将降低8%

5)节能系统可以降低多少成本?
将节省10%的天然气(气)

6)公司在子公司的投资有1.01亿令吉的减值,这是什么?
这些是新管理层进入公司之前的减值。它涉及舒适橡胶手套工业S / B(RM9,030万)和PBT S / B(10.9m)。这些是很久以前发生的事情。如果将来会计准则允许,则可以冲销减值准备

意见:很久以前,减值通常很难逆转,因此投资者不必期望过高

7)我看到年度报告的大部分市场份额都在马来西亚。为什么不卖给美国更多?
实际上,它们在马来西亚出售,但最终它们被运到国外

8)FDA进口警报是否会影响公司?
完全没有效果。

9)现货订单的大概价格是多少?
大约是12%,价格肯定更高,其中大多数不会超过100美元

意见:我们可以看到老板对手套业务非常热心,而不是只看利润的公司。管理层表示,做生意必须着眼于长期,而不仅仅是牺牲短期内的长期客户,因为短期内会有更高的利润。目前,舒适手套的价格确实低于其他手套制造商,但是对于较小的公司,这种方法也更合适。毕竟,他们没有其他大公司那样多的不同客户。我们还看到了关有元先生,他也赞扬了管理层的表现,并提到明年应该给管理层更多的奖励。初步计算,假设在卖出26美元之前,现在卖出33美元,那么该公司的营业额将高达1.94亿林吉特,比上一季度的1.53亿林吉特增加了4100万林吉特。这个表现还不错。

注意:

老板还提到TopGlov现货订单高达170美元。

下个季度的Likeky Comfort PAT约为35密耳,每股收益5.6-6.0美分,基于远期PE20,折合为3.50-4.00。

Koon先生补充了管理层,并表示将收购更多股份。
转贴:
安慰:董事长在股东周年大会上的讲话-尹耀贤
作者:尹耀贤发布日期:星期二,2020年6月30日,晚上11:25

今天早上,我参加了舒适手套年度大会。我右边的人是董事长,左边的人是首席执行官。我想在这里记录一下主席在股东周年大会上的发言。


主席公开表示,由于Covid 19大流行,对手套的持续需求远远超过了供应。结果,该公司可以轻松提高其产品的销售价格。自第二季度开始以来,他们每月将其销售价格提高5-10%。他们向长期客户出售更便宜的产品,并向其他客户出售更高的价格。他们甚至在更高的售价下也没有困难,因为订单不断增加。

最近增加了6条生产线,他们每周7天,每天24小时不间断地工作,以生产尽可能多的手套。

销售的增加不会使公司付出任何代价。这是纯利润。

注意:我有义务告知您Comfort是我的主要投资资产之一。我不是要您购买来推高股价以丰富我。如果您决定购买,我对您的盈亏不承担任何责任
个人分享,買卖自负。
2127:rm3.70
7803:rm3.64
💪💪手套股全部回来了,净利能见度到2021财政年。

2020年7月2日星期四

Homeriz 5160 家丽资 62仙投资

-Homeritz Corp Bhd是一家投资控股公司,设计,制造和销售室内装饰家具产品。 该公司提供的室内装饰家具产品包括皮革和织物沙发,餐椅和床架。 和Eritz品牌的生活用家具产品。 它还参与房地产投资活动; 以及家具和家具零件的设计,制造和销售。 该公司的主要收入来自亚太市场。

-HLG:

Maintain BUY, TP: RM0.72. After rolling over our valuation year to FY21 and adjusting for changes in earnings our TP falls from RM0.76 to RM0.72 pegged to an unchanged 10x PE multiple. We continue to like Homeritz due to healthy net cash per share per share of RM0.27


-产品热销 订单大增 家具业逆势疯赶工

http://www.enanyang.my/%E8%B4%A2%E7%BB%8F%E6%96%B0%E9%97%BB/%E3%80%90%E7%8B%AC%E5%AE%B6%E3%80%91%E4%BA%A7%E5%93%81%E7%83%AD%E9%94%80-%E8%AE%A2%E5%8D%95%E5%A4%A7%E5%A2%9E-%E5%AE%B6%E5%85%B7%E4%B8%9A%E9%80%86%E5%8A%BF%E7%96%AF%E8%B5%B6%E5%B7%A5

-


Fundamental Analysis: Lii Hen vs Homeritz


In my previous post, I made some highlights on the Malaysian furniture industry. In this article, I would analyse the two furniture companies which I believe are well positioned to ride out this economic uncertainty. To be honest, there are many other companies to analyze within this industry and I may have only analyzed a small portion of it. Here are the list of companies that I have gone through:
  • Homeritz
  • Lii Hen
  • Evergreen
  • Heveaboard
  • Jay Corp
  • Poh Huat
  • SWS
I am sure that there are some I have missed out on but among these, I believe Lii Hen and Homeritz are worth considering. The table below is a summary of what my analysis indicates.


Current price was on 24.4.2020

Analyzing the two companies was not simple, both companies had different attractive points. If you noticed, Lii Hen has many characteristics of a good company (good growth & strong cash position) but no investment should ever be bought based on good growth alone. The PRICE we pay for the investment is equally important and Lii Hen may be selling at a discount.
Next up, we have Homeritz. The company experienced practically zero growth (actual: 3%) but it has been enjoying remarkable profit margins. Among the analyzed companies, Homeritz has the highest profit margins and the only company with double digits (average profit margin = 16.7%). Moreover, the cash position in Homeritz was equal to RM 0.27 per share! If you would refer to the table below, you’d see that Homertiz has a cash position of 82 million while the company’s market capitalization is 142 million (the cash is more than half its value now!)


In all aspects except debt, Lii Hen shows promising figures. The revenue and profit has been growing at a CAGR of 14%. The cash position and working capital has been growing steadily as well. However, I do not believe that Lii Hen’s 14% growth rate is sustainable. Assuming that the 14% growth rate is maintained, Lii Hen’s revenue would double to RM 1.67 billion by 2024. The recent slowdown and pandemic would drastically reduce furniture sales. I believe the future growth may fall between 3% to 5%.
Homeritz has been stagnant with its growth but it does make predicting it’s future earnings relatively simple. Moreover, the significantly higher profit margins enjoyed by Homeritz would suggest its products are within the premium product range and enjoys an above average profit. Refer to the chart below for Lii Hen’s and Homeritz’s profit margins in comparison to industrial averages. As you can see, Homeritz’s profit margin is between 10% to 20% while Lii Hen’s is between 4% to 12%. However, the industrial average is only 2.4%.


Branding
When it comes to branding, I prefer Homeritz as the company markets its products under one brand name, Eritz. Although, the company is currently in the ODM business, I believe that the company can make the switch from ODM to OBM with its existing Eritz brand.


Homeritz’s brand

Lii Hen has yet to market its products under one brand name. As mentioned in my previous post. The move towards an OBM model would benefit the company in terms of higher profit margins and Homeritz’s significantly higher profit margins with its Eritz branding may be a key reason for its success.
Conclusion
As Lii Hen grows, the business would eventually require less capital expenditures and would translate to potentially higher dividend returns. However the lack of a branding is regrettable. Based on my estimates, the company is worth between RM 2.50 to RM 3.20. The current price may provide a 20% margin of safety.
Homeritz on the other hand has a cash position which is worth RM 0.27 while trading at RM 0.48. Moreover, assuming that the business remains constant without growth, the company is worth RM 0.65 to RM 0.77. The current price may provide a 25% margin of safety.
I already own shares of Homeritz and am looking towards puchasing Lii Hen. Therefore, my analysis would be biased.
基本面分析:Lii Hen vs Homeritz

在我以前的文章中,我对马来西亚家具业做了一些重点介绍。在本文中,我将分析两家相信可以很好地克服这种经济不确定性的家具公司。老实说,在这个行业中还有许多其他公司需要分析,而我可能只分析了其中的一小部分。以下是我经历过的公司列表:
荷马里兹
黎亨
常绿
橡胶板
杰伊公司
宝发
速帝世界总冠军大赛
我敢肯定我错过了一些,但是在这些之中,我相信Lii Hen和Homeritz值得考虑。下表是我的分析表明的摘要。

当前价格为24.4.2020
分析两家公司并非易事,两家公司具有不同的吸引力。如果您注意到,Lii Hen具有良好公司的许多特征(良好的增长和强大的现金状况),但仅凭良好的增长就不应购买任何投资。我们为投资支付的价格同样重要,Lii Hen可能会打折出售。
接下来,我们有荷马里兹。该公司的增长几乎为零(实际:3%),但利润率却很高。在所分析的公司中,荷马里兹的利润率最高,也是唯一一位两位数的公司(平均利润率= 16.7%)。此外,荷马兹的现金头寸等于每股0.27令吉!如果您参考下表,您会发现Homertiz的现金头寸为8200万,而公司的市值为1.42亿(现金现在是其市值的一半以上!)

除债务外,在所有方面,黎亨均显示出良好的前景。收入和利润一直以14%的复合年增长率增长。现金状况和营运资金也一直稳定增长。但是,我认为Lii Hen的14%的增长率是可持续的。假设维持14%的增长率,Lii Hen的收入到2024年将翻一番,达到16.7亿林吉特。近期的放缓和大流行将大大减少家具的销售。我相信未来的增长可能会落在3%至5%之间。
荷马里兹的增长一直停滞不前,但确实使预测其未来收益变得相对简单。而且,荷马利兹公司获得的利润率明显更高,这表明其产品属于优质产品范围,并且利润高于平均水平。请参阅以下图表,了解Lii Hen和Homeritz与行业平均水平相比的利润率。如您所见,荷马里兹的利润率在10%至20%之间,而莉恩(Lii Hen)的利润率在4%至12%之间。但是,行业平均水平仅为2.4%。

品牌推广
在品牌方面,我更喜欢Homeritz,因为该公司以一个品牌Eritz销售产品。尽管该公司目前从事ODM业务,但我相信该公司可以使用其现有的Eritz品牌从ODM转换为OBM。

荷马兹的品牌
Lii Hen尚未以一个品牌名称销售其产品。正如我以前的帖子中提到的。朝着OBM模式的转变将使公司从更高的利润率中受益,荷马兹的Eritz品牌带来的更高的利润率可能是其成功的关键原因。
结论
随着Lii Hen的发展,该业务最终将需要更少的资本支出,并可能转化为更高的股息回报。然而,缺乏品牌令人遗憾。根据我的估计,该公司的市值介于2.50令吉至3.20令吉之间。当前价格可能提供20%的安全裕度。
另一方面,荷马里兹的现金头寸价值为0.27令吉,而交易价为0.48令吉。此外,假设业务保持不变而不增长,公司的市值将介于0.65令吉至0.77令吉。当前价格可能提供25%的安全边际。
我已经拥有Homeritz的股份,并且正在寻求购买Lii Hen。因此,我的分析将有偏见
广告


--低估,庄拉低对付短期投机客,全年eps估计为9仙,取pe=9倍,股价为81仙,近5%的周息率,净现有8113万,profit margin :16%
Roe %:15

Nta:55 sen

--贸战开打·美订单转东盟·马家具业因祸得褔 - 星洲日報/投資致富‧企業故事 | I3investor
https://klse.i3investor.com/blogs/sinchew_company_story/2019-09-18-story225416.jsp

--家丽资机构(HOMERIZ,5160,主板消费产品服务组)向来对美国市场较为陌生,惟该公司于今年为止签下了8个新的美国市场客户,使它有意在未来3至5年进行扩张计划,实质进展则胥视客户需求而定。


该行预期大马2019年的家具出口增长,将达6.1%至27亿美元(约113亿令吉),比2018年成长3.1%高。在越南市场方面,预料其2019年出口到美国家具产品将增长20%至120亿美元,延续2018年增长16%的增长动力。
--HOMERIZ (5160) : 冷眼从 FYE 31/8/2014 开始到 FYE 31/8/2019 都是它的三十大股东之一,最高排名第四名,最低排名也只是第十二名,最低拥股量为 1,700,000 @ 0.567% 和最高拥股量为 4,020,000 @ 2.010%。如果你认同冷眼的眼光,那就要多留意这股,看看是否可以收下。盈亏自负。
--家丽资机构丰隆认为家丽资机构(HOMERIZ,5160,主板消费产品服务组)是最稳定的家具股,前景转为正面,该公司将受惠于更多来自美国的订单(受中美贸易战影响)和美元走强。该公司也正积极扩充业务,包括购买更多机械以进一步加强自动化。

丰隆在该公司10月杪业绩出炉时已上调财测,目前保持财测不变。保持“买进”评级和目标价84仙。